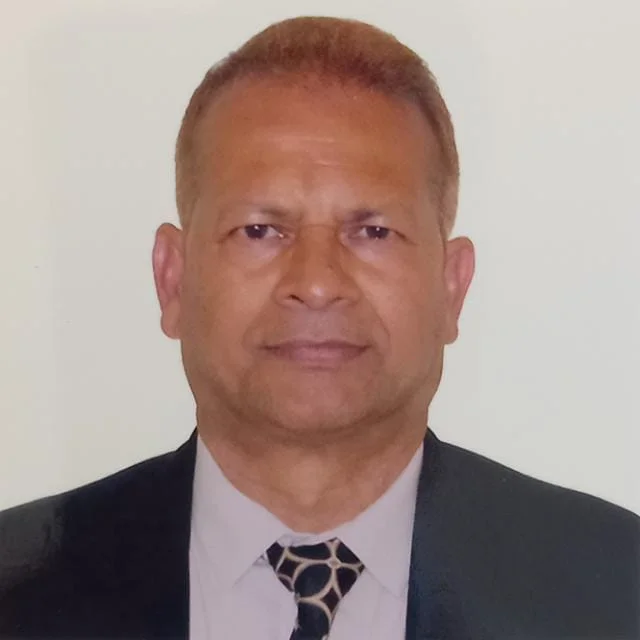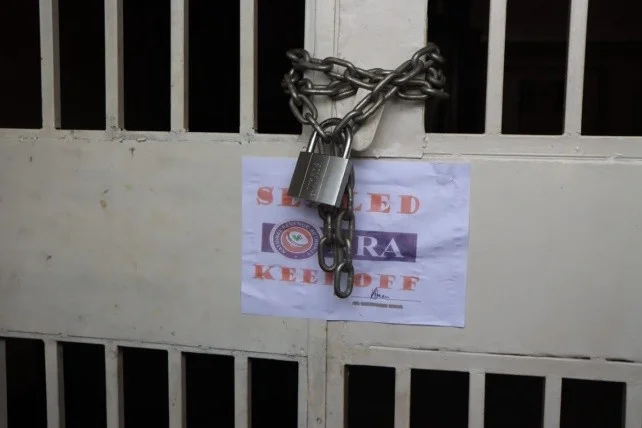
Officials from the National Revenue Authority (NRA) sealed the offices of Yada Hashim Williams Esq. At No. 7 Walpole Street, Freetown, on Wednesday, May 20, 2026, amid claims of unpaid rental income taxes. Yada Hashim Williams Esq. Stated that the action occurred despite a High Court Order restraining such an action, describing it as "high-handed and lacking factual and legal basis."
Williams asserted that "the premises were reopened shortly afterward, which he argued effectively reversed what he termed an illegal action by the Authority." He maintained that he does not owe any rental income taxes for a property occupied by the United Nations Development Programme (UNDP) at Fourah Bay Close, Off Main Motor Road, Wilberforce. Williams explained that "the tenancy arrangement explicitly provides for taxes to be deducted at source by the tenant before rental payments are remitted to him," and that "rent payments are made net of Government of Sierra Leone taxes on rents." He added that "under the arrangement, applicable taxes are withheld by the tenant before rent is paid to him," and copies of the tenancy agreements were submitted to the NRA on March 4, 2026. Williams stated that "Sierra Leonean law imposes a mandatory obligation on institutional tenants to withhold taxes on rent payments made to landlords," making the UNDP arrangement legally mandated. He also argued that "provisions of the Income Tax Act authorize enforcement actions against premises directly connected to unpaid rental income tax obligations and not unrelated properties."
NRA's Justification for Action
The National Revenue Authority (NRA) stated that the sealing of the legal practitioner’s office was undertaken over what it described as outstanding rental income tax liabilities spanning from 2019 to 2025. According to the NRA, the Commissioner-General had established reasonable grounds to believe that the taxpayer failed to remit the correct taxes allegedly owed to the Government of Sierra Leone. The Authority clarified that its action was carried out by its Domestic Tax Department, pursuant to Section 155A of the Income Tax Act 2000 and Section 50(1) of the Goods and Services Tax Act 2000.
The NRA maintained that tenancy arrangements involving the United Nations Development Programme do not extinguish or nullify statutory tax obligations imposed on landlords under Sierra Leonean law. The Authority further explained that while the UNDP enjoys diplomatic privileges and immunities, such protections do not exempt private property owners from meeting their tax obligations to the state. The NRA warned that failure to comply could result in enforcement actions, including sealing or restricting access to office and residential premises associated with the taxpayer anywhere within Sierra Leone.
The Authority reiterated the importance of compliance among landlords and taxpayers receiving rental income, stating that the matter would only be deemed resolved upon full settlement of the tax debt. The NRA emphasized that adherence to tax regulations remains vital to strengthening domestic revenue mobilization, accountability, and national development financing.
Lawyer's Defense and Allegations
Yada Hashim Williams Esq. Characterized the sealing of his offices as unlawful, malicious, and an act of contempt against a High Court injunction. He stated that "the sealing of the offices of Yada Williams & Associates at No. 7 Walpole Street, Freetown, on Wednesday, 20th May 2026, despite what he described as a valid High Court Order restraining such action." Williams added that "the premises were reopened shortly afterward, which he argued effectively reversed what he termed an illegal action by the Authority," accusing the National Revenue Authority of "acting in a manner he described as high-handed and lacking factual and legal basis."
Legal proceedings commenced on May 18, 2026, challenging the NRA's assertions regarding alleged unpaid taxes. Williams maintained that he does not owe any rental income taxes in connection to a property occupied by the United Nations Development Programme (UNDP) at Fourah Bay Close, Off Main Motor Road, Wilberforce. He stated that "he does not owe any rental income taxes in relation to a property located at Fourah Bay Close, Off Main Motor Road, Wilberforce, occupied by the United Nations Development Programme." Williams clarified that "the tenancy arrangement explicitly provides for taxes to be deducted at source by the tenant before rental payments are remitted to him."
Williams further explained that "rent payments are made net of Government of Sierra Leone taxes on rents," and "under the arrangement, applicable taxes are withheld by the tenant before rent is paid to him, noting that copies of the tenancy agreements had already been submitted to the National Revenue Authority on 4th March 2026." He emphasized that "Sierra Leonean law imposes a mandatory obligation on institutional tenants to withhold taxes on rent payments made to landlords," asserting that "the arrangement involving the United Nations Development Programme was legally mandated and not optional."
Williams questioned the legality of sealing his Walpole Street offices rather than the Wilberforce property, stating that "provisions of the Income Tax Act authorize enforcement actions against premises directly connected to unpaid rental income tax obligations and not unrelated properties." He reiterated that his office location has no direct connection to the property for which the tax dispute arose.
Property and Tenancy Details
The property central to the dispute is located at Fourah Bay Close, Off Main Motor Road, Wilberforce. The United Nations Development Programme (UNDP) has occupied this property since September 2018. According to Yada Hashim Williams Esq. The tenancy agreements for this property stipulate that "rent payments are made net of Government of Sierra Leone taxes on rents." Copies of these tenancy agreements were formally submitted to the National Revenue Authority (NRA) on March 4, 2026.
The National Revenue Authority, however, stated that "the sealing of the legal practitioner’s office was undertaken over what it described as outstanding rental income tax liabilities spanning from 2019 to 2025." The NRA confirmed that "the Commissioner-General had established reasonable grounds to believe that the taxpayer failed to remit the correct taxes allegedly owed to the Government of Sierra Leone." The Authority maintains that "tenancy arrangements involving the United Nations Development Programme do not extinguish or nullify statutory tax obligations imposed on landlords under Sierra Leonean law." It added that "while the UNDP enjoys diplomatic privileges and immunities, such protections do not exempt private property owners from meeting their tax obligations to the state."
The NRA reiterated that "failure to comply could result in enforcement actions, including sealing or restricting access to office and residential premises associated with the taxpayer anywhere within Sierra Leone." The Authority emphasized that "the matter would only be deemed resolved upon full settlement of the tax debt," and that "adherence to tax regulations remains vital to strengthening domestic revenue mobilization, accountability, and national development financing."
Legal and Statutory Context
Yada Hashim Williams Esq. Was instructed to settle an alleged outstanding liability by Friday, May 15, 2026. He maintained that he does not owe any rental income taxes in relation to a property located at Fourah Bay Close, Off Main Motor Road, Wilberforce, occupied by the United Nations Development Programme (UNDP). Williams stated that "the tenancy arrangement explicitly provides for taxes to be deducted at source by the tenant before rental payments are remitted to him." He added that "rent payments are made net of Government of Sierra Leone taxes on rents," and "under the arrangement, applicable taxes are withheld by the tenant before rent is paid to him." Williams cited Section 120 of the Income Tax Act No. 8 of 2000 and Section 11 of the Finance Act No. 2 of 2018, asserting that "Sierra Leonean law imposes a mandatory obligation on institutional tenants to withhold taxes on rent payments made to landlords." He emphasized that "the arrangement involving the United Nations Development Programme was legally mandated and not optional." However, the National Revenue Authority argued that tenancy arrangements with the UNDP do not extinguish statutory tax obligations on landlords.